Arkansas Is One Decision Away From America’s First Big Brine Lithium Plant
By the end of this year, Standard Lithium and Equinor aim to decide whether to build the first commercial-scale plant in the United States for drawing lithium out of underground brine. If they go ahead, some of America’s battery lithium will come from the same rock that has produced its oil for a century.
By the end of this year, Standard Lithium and its partner Equinor aim to take a final investment decision on their South West Arkansas project, a plant with a budget of $1.45 billion in the Smackover Formation, an oil-bearing layer of rock beneath southern Arkansas and East Texas. In the partners’ words, it would be the first commercial-scale direct lithium extraction plant in the United States.
The decision has not been taken yet, and the 2029 start date is a target rather than a schedule. But the project has now cleared most of the hurdles that usually stop plans like it.
What is being decided
The project belongs to Smackover Lithium, a joint venture owned 55 per cent by Standard Lithium and 45 per cent by Equinor, the Norwegian energy company. Its site lies about 15 miles west of Magnolia in Columbia County, near the borders with Texas and Louisiana.
The first phase is designed to make 22,500 tonnes a year of battery-quality lithium carbonate, with first commercial production targeted for 2029. The partners’ feasibility study models a 20-year plant life.
A final investment decision is the point at which a project stops being a plan. Once it is taken, the partners say, their contractors will receive full notice to proceed, and construction will begin.
A different way to get lithium
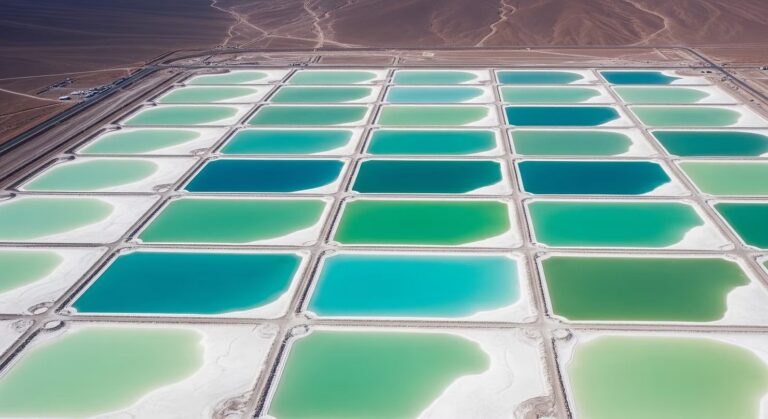
Most of the world’s brine lithium comes from evaporation ponds, where salty water sits in the sun until the lithium concentrates. Direct lithium extraction skips the ponds. Operators drill wells much as an oil company would, pump the brine up, take the lithium out and return the brine underground. Chevron, which is also exploring the method, describes it as faster and more efficient than traditional extraction, with a smaller environmental footprint.
In Arkansas, the plant will use a process licensed from Aquatech. Standard Lithium has been refining the technology for years at its demonstration plant in El Dorado, and ran a further proof-of-technology pilot at the project site itself. The lithium will be refined into battery-quality carbonate on site, so none of it needs to travel abroad for processing.
Why an oilfield
The Smackover has been an oil province since the 1920s, according to the Federal Reserve Bank of Dallas. What draws lithium companies now is the brine beneath it, which carries unusually high lithium concentrations.
The oil industry has noticed. ExxonMobil bought the rights to 120,000 gross acres of the Smackover in 2023, and has since expanded its position. Chevron announced about 125,000 net acres across northeast Texas and southwest Arkansas in June 2025. Equinor is already in, as Standard Lithium’s partner.
Southern Arkansas brings something less obvious than oil: a regulator used to brine. The Smackover brine was first found during the oil discoveries of the 1920s, but it was in the 1960s that industry recognised it as a resource in its own right, and the region went on to build some sixty years of bromine production from it. That history, more than the oil, established the regulatory framework the lithium industry now inherits. Arkansas’s Oil and Gas Commission has already approved the project’s brine unit and set a royalty for lithium. For a first-of-its-kind plant, a settled rulebook matters almost as much as the geology.
Three boxes ticked, one to go
The partners set themselves four tasks before a final investment decision. Three are done.
| What the decision needs | Where it stands |
|---|---|
| Construction contracts | Signed for both the wellfield and the processing plant (May 2026) |
| Federal environmental review | Completed by the Department of Energy, with a finding of no significant impact. The company expects no further federal reviews before the decision. |
| Customers | 16,000 tonnes a year on firm take-or-pay terms, plus an option on 4,000 more (September 2026) |
| Project debt | About $1.1 billion, being arranged with export credit agencies |
The customer list is the clearest sign of confidence. Trafigura, one of the world’s largest commodity traders, has a 10-year take-or-pay agreement for 8,000 tonnes a year. Smackover Lithium can also choose to sell it up to 4,000 tonnes more, but that is the producer’s option, not a firm commitment. LG Energy Solution, which started production at its new plant in Lansing, Michigan in August, has signed for another 8,000 tonnes a year.
The feasibility study puts average cash operating costs at $4,516 a tonne, and all-in costs at $5,924.
Federal support has spanned two administrations. The Department of Energy awarded the project a $225 million grant in January 2025, and in April 2025 it was named one of the first priority mineral projects under Executive Order 14241, which fast-tracks permitting.
Where it fits in America’s lithium story
America produces little lithium of its own. The US Geological Survey keeps the country’s production figures confidential to protect company data, but says the United States relies on imports for more than half the lithium it uses. Two very different projects are set to change that.
The first to arrive should be Thacker Pass in Nevada, a clay deposit being developed by Lithium Americas with General Motors. It is targeting mechanical completion in late 2027, with production ramping up towards 40,000 tonnes a year. Arkansas would follow in 2029, as the first plant to show whether oilfield brine can supply the country at scale.
If it works, more could follow. Smackover Lithium plans to double the Arkansas plant to 45,000 tonnes a year, and Standard Lithium is studying a further project in East Texas. EnergyX, a Texas company, plans a commercial plant near Texarkana that it says will reach 50,000 tonnes a year of lithium hydroxide by 2030.
What could still go wrong
The money is not yet in the bank. Customers and contractors are signed, but the project debt still has to close, and until it does the decision date is a target, not a promise.
Price is the bigger question. The feasibility study assumes lithium carbonate sells for $22,400 a tonne, the average of Fastmarkets’ 20-year forward price curve. On 5 November, battery-grade carbonate in China traded at about $12,100 a tonne before VAT, according to Shanghai Metals Market. Low operating costs give the plant room to absorb a weak market, but a long one would stretch the payback on a $1.45 billion build.
Then there is scale. Years of work at the El Dorado demonstration plant, and a proof-of-technology pilot at the project site, are encouraging, but neither is the same as running a full commercial plant for twenty years, and no direct extraction plant in the United States has yet done so.
Demand at home has also shifted. Federal tax credits for buying electric vehicles ended for vehicles bought after 30 September 2025. Grid storage is picking up some of the slack: LG Energy Solution’s new Lansing plant makes cells for energy storage as well as for cars.
The Ledger
America has never lacked lithium in the ground. What it has lacked is a plant that turns its unusual deposits into battery-grade product at a competitive cost, and a way of financing the first one. Arkansas now has almost everything that takes: the contracts, the customers, the federal clearance and a regulator that knows brine. What remains is the money, and the patience to build through a weak price. If the decision comes this winter and the plant delivers in 2029, the oilfields of the American South will have found a second century of work, and the rest of the Smackover will not be far behind.
Smackover Lithium, Definitive Feasibility Study results, filed with the US Securities and Exchange Commission on 3 September 2025 (budget, production, plant life, costs, price assumption, location). Standard Lithium, South West Arkansas project page (process, pilot, regulatory approvals, grant, priority status, expansion plans). Standard Lithium, construction contract announcement, 26 May 2026 (contracts, notice to proceed). Standard Lithium, second-quarter 2026 results, 10 August 2026 (federal environmental review). Smackover Lithium, offtake announcement, September 2026 (customers). Standard Lithium, investor presentation, September 2026 (decision timing, project debt). Federal Reserve Bank of Dallas, October 2025 (Smackover history). ExxonMobil, 13 November 2023 (acreage). Chevron, 17 June 2025 (acreage, description of direct extraction). LG Energy Solution, 18 August 2026 (Lansing plant). US Geological Survey, Mineral Commodity Summaries 2026 (US production and imports). Lithium Americas, Thacker Pass overview. EnergyX, Project Lonestar. Shanghai Metals Market, 5 November 2026 (lithium carbonate price). Internal Revenue Service, clean vehicle tax credits.
Read next
All insights →
 Newest on The RegisterDr Francisco TrinidadFormer Director of Battery Technology, Exide · Alpha Beta SocietyRead the profile →